Mon - Sat : 11am - 7pm
Mon - Sat : 11am - 7pm
 Personal Loans
 Payday Loans
 Business Term Loans
 Debt Consolidation Loans
 Vacation Loans
 Investment Loans
 Wedding Loans
 Renovation Loans
 Education Loans
 Small Business Loans
 Moneylender Loans
 Medical Loans
 Foreigner Loans
 Borrow Money Online
 Low Interest Rate Loans
 Personal Loan Calculator
 Credit Card Consolidation
 Emergency Loans
 Legal Loans
 Small Cash LoansPersonal Loans
Payday Loans
Business Term Loans
Debt Consolidation Loans
Vacation Loans
Investment Loans
Wedding Loans
Renovation Loans
Education Loans
Small Business Loans
Moneylender Loans
Medical Loans
Foreigner Loans
Borrow Money Online
Low Interest Rate Loans
Personal Loan Calculator
Credit Card Consolidation
Emergency Loans
Legal Loans
Small Cash Loans

by EZ Loan Pte Ltd

Updated 1 September 2026
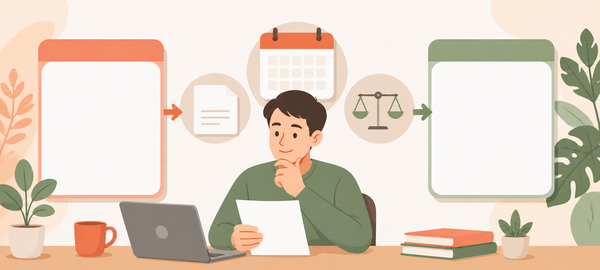
On 31 August 2026, the Ministry of Law announced a mandatory three-business-day cooling-off period for unsecured loans from licensed moneylenders, except business loans, starting on 15 September 2026. Saturdays, Sundays and Singapore public holidays are excluded.[1]
Start date: 15 September 2026.
Coverage: unsecured loans from licensed moneylenders, except business loans.
Duration: three business days.
Excluded days: Saturdays, Sundays and Singapore public holidays.
Cancellation treatment: no interest; where the approval fee was deducted upfront, a capped portion may be retained and total repayment cannot exceed the loan principal.[1]
Use the final Ministry of Law source and your written documents to confirm the rule that applies to a particular loan.
Under the previous treatment described in the announcement, licensed moneylenders could keep the full loan approval fee and any accrued interest when a borrower cancelled a loan.[1] This comparison does not replace the law and contract that apply to an individual transaction.
The mandatory three-business-day period begins for covered unsecured loans. Saturdays, Sundays and Singapore public holidays are excluded from the count. Business loans are outside the new framework.[1]
| Status | Before 15 September 2026 | From 15 September 2026 |
|---|---|---|
| Changed: coverage | No mandatory three-business-day framework described in the source comparison | Applies to unsecured loans from licensed moneylenders, except business loans |
| Changed: counting | No mandatory three-business-day count described in the source comparison | Three business days, excluding Saturdays, Sundays and Singapore public holidays |
| Changed: interest | Accrued interest could be kept under the previous treatment | No interest for a borrower who cancels within the cooling-off period |
| Changed: approval fee | The full approval fee could be kept under the previous treatment | Only a permitted portion may be retained, subject to the announced cap and the approval fee charged |
| Changed: repayment | No new cancellation formula under the previous treatment | Amount disbursed plus the permitted retained portion, with total repayment not exceeding principal |
For principal of S$5,000 or less, a lender may retain up to S$50 from the approval fee, but not more than the approval fee charged. For principal above S$5,000, the limit is up to 3.5% of principal, again capped at the approval fee charged.[1]
The rule therefore has two limits. The applicable percentage or fixed ceiling sets one limit, and the approval fee actually charged sets the other. A lender cannot retain more than the announced ceiling or more than the approval fee charged. These are maximums, not automatic charges.
The borrower repays the amount disbursed plus the permitted retained portion of the approval fee. The total amount repaid cannot exceed the loan principal.[1] The amount disbursed matters because an upfront fee can mean the cash received is lower than the principal stated in the contract.
The public Registry borrower guidance continues to tell borrowers to consider alternatives, borrow only what they need and can repay, understand the repayment schedule, interest rate and fees, shop around and avoid rushing into a loan.[2] The cooling-off framework does not remove those checks.
The Registry also says a moneylender must explain the terms in a language the borrower understands and provide a copy of the loan contract.[2] Keep that copy. A short cancellation period is easier to assess when the principal, net disbursement, interest basis, fees, instalments and total repayment are written clearly.
The Registry’s licensed-list guidance also says licensed moneylenders must meet the borrower in person at the approved place of business for physical face-to-face identity verification before granting a loan. It warns that scammers may imitate licensed businesses and that licensed moneylenders are not allowed to solicit loans through text messages, phone calls or social media platforms.[3] Those verification checks remain relevant when you review a new loan.
EZ Loan’s public legitimacy page identifies the consumer brand as EZ LOAN PTE. LTD. and states Licence No. 19/2026.[5] It lists two physical locations:
Marina Square: 6 Raffles Boulevard, #03-308, Marina Square, Singapore 039594.
Beach Road: 3 Beach Road, #01-4853, Singapore 190003.[5]
The same page says EZ Loan completes face-to-face verification before granting a loan and puts rates and fees in writing.[5] Face-to-face verification is a baseline requirement for licensed moneylenders, not a special exemption. Use the official Registry to match the exact legal name, licence number, approved address and website before sharing personal information.[3]
The new framework replaces the previous treatment described in the announcement, under which a lender could keep the full approval fee and accrued interest when a borrower cancelled. From 15 September 2026, the framework removes interest for an eligible cancellation and limits the retained approval fee.[1]
The framework covers unsecured loans from licensed moneylenders, except business loans.[1] The supplied sources do not support extending it to secured loans.
No. Saturdays, Sundays and Singapore public holidays are excluded from the three business days.[1]
No. The S$50 and 3.5% figures are ceilings, and the retained amount cannot exceed the approval fee charged.[1] The actual documents still matter.
Sure, you may ask the customer service officer to provide more information and details on this.
The framework changes the treatment of an eligible cancellation from 15 September 2026: three business days, no interest and a capped retained portion of the approval fee, with repayment tied to the amount disbursed and a ceiling at the principal.[1] Read the Ministry of Law announcement together with the written terms that apply to your loan.
EZ Loan’s useful role in this explainer is concrete verification. Check the legal identity and listed branches against the Registry, and review the written rate and fee information for the loan you are considering.[3][5]
This article is general information, not legal or financial advice. Your contract and the applicable MinLaw rules control.
Recent Insights
Top 5 licensed moneylenders in Singapore: which has the lowest monthly repayment?Bank Personal Loan Rejected in Singapore? What to Check Before Applying AgainTop licensed moneylenders in Singapore: 5 options to compare
You can start your application online, visit one of our offices, or connect with us via WhatsApp—whichever is most convenient for you.
Visit one of our branches for a free consultation, present the necessary documents, and finalise the loan agreement.
Some approved loans may be disbursed on the same day. Timing depends on assessment, document verification and the required face-to-face identity verification.
Speed up your application with MyInfo
Have your personal details filled in automatically. This also helps us to approve your loan more quickly!
Retrieve MyInfo

 Beach Road